
When your fixed mortgage deal ends, you do not automatically move onto a good new rate — you drift onto your lender’s standard variable rate, usually at a much higher cost. The good news is that the end of a fix gives you real leverage: your balance is known, your payment history is established, and lenders compete for low-risk borrowers. This guide sets out a timeline, the choice between a product transfer and a full remortgage, the fees to check, and what to do if rates might fall.
Start Six Months Early: A Timeline That Works
Six months before your deal ends, find the exact end date. Check your original mortgage offer, your annual statement or your lender’s app — do not rely on memory, because an early repayment charge can apply right up to that date. Note your current balance, your monthly payment, and roughly what your home is worth now, because those figures decide your loan-to-value band, and loan-to-value decides the rates you are offered.
Three months out, start proper comparisons. Most lenders let you reserve a new deal three to six months in advance, and reserving is not a commitment to complete on it — it is an option you can walk away from if something better appears. Get quotes from your current lender, look at the wider market, and if you use a broker, ask them to show you the total cost over the deal period, not just the headline rate. In the final month, aim to complete the switch on the day after your fix ends. For background on how the wider market shapes the deals on offer, see our explainer on interest rates and mortgages for homeowners in 2026.
Product Transfer or Full Remortgage?
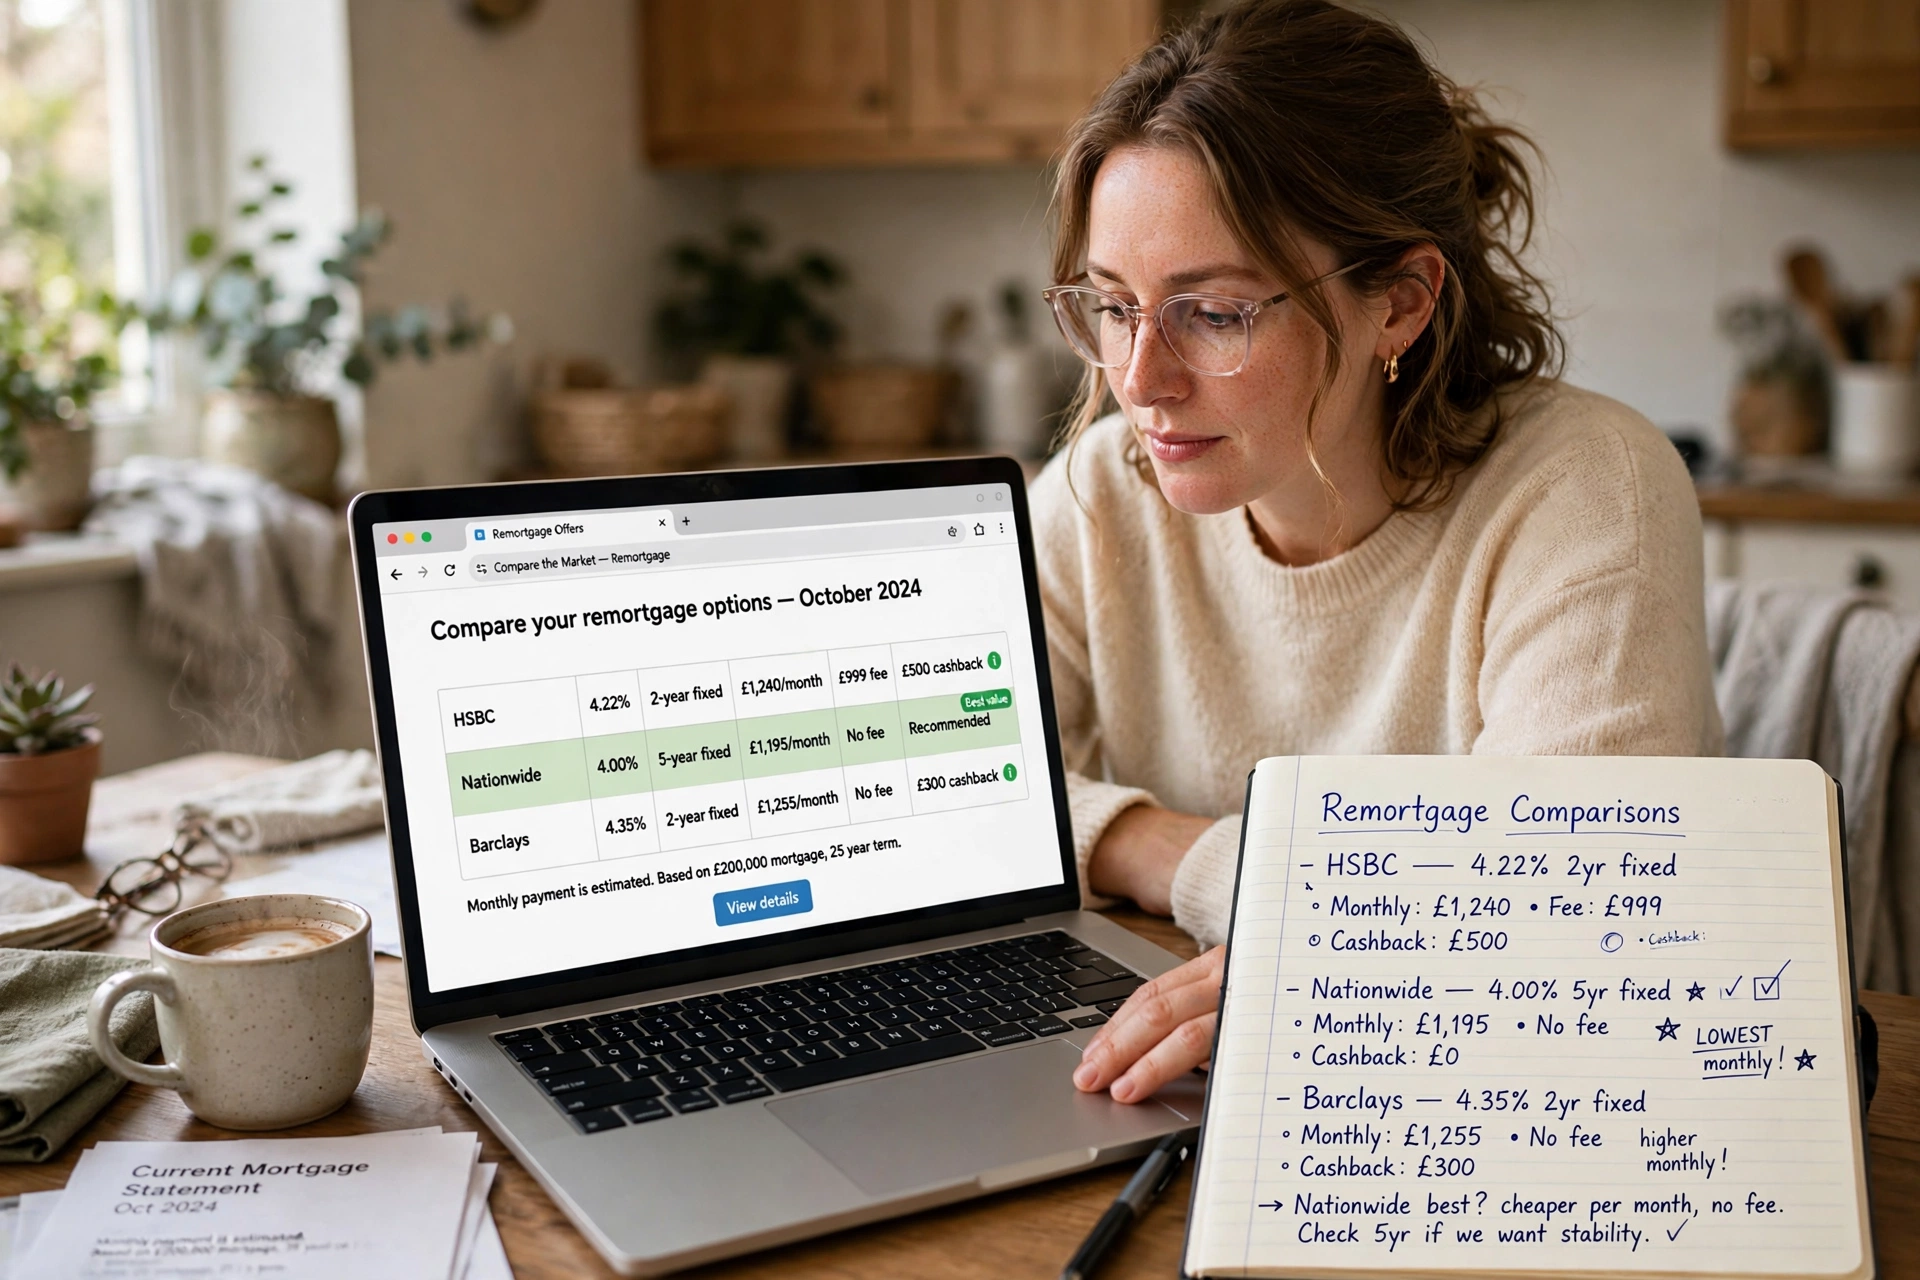
A product transfer means staying with your current lender and moving onto a new deal with them. It is usually the fastest route: often no new valuation, no legal work, minimal affordability checks, and sometimes a switch completed online in minutes. Transfer rates are often competitive, but not always the cheapest on the market. A full remortgage means moving your borrowing to a new lender. It takes longer, typically four to eight weeks, and involves an application, a valuation and conveyancing, but many remortgage deals include free valuation and free legal work to win your business, and the rate saving over two or five years can run into thousands of pounds.
Choose a product transfer if speed matters, if your circumstances have changed in ways a new lender might question — a recent job change or a dip in your credit record — or if its rate is close to the best market rate once fees are counted. Choose a full remortgage if the rate gap is meaningful, or you want to borrow more, change the term, or move from interest-only to repayment. Either way, compare like with like: same term, same deal length, all fees included.
What Drifting onto the SVR Really Costs
The standard variable rate, or SVR, is set by your lender and can change at any time. It is commonly two or more percentage points above a competitive fixed rate. Put numbers on it: on a £250,000 repayment mortgage with 20 years left, a fix at 4.2 per cent costs about £1,541 a month. On an SVR of 7.5 per cent, the same loan costs about £2,014 a month — roughly £473 more every month, or over £5,600 a year, for exactly the same house and the same debt. Six months of drifting could cost close to £2,800. A short spell on the SVR is only deliberate if you are about to move, pay off the loan, or need freedom from early repayment charges for a few weeks. Otherwise it is a waiting room, not a destination, and the meter is running.
Fees, Credit Files and Timing Traps
Four costs catch people out. First, early repayment charges: leaving before your deal’s end date can cost 1 to 5 per cent of the balance, so time completion for the day after the fix ends. Second, arrangement or product fees on the new deal, often £999 or more; a lender may offer a fee-free deal at a slightly higher rate, and on smaller balances the fee-free option frequently wins — divide the fee by the months in the deal to see its true monthly weight. Third, valuation and legal fees on a full remortgage, often covered by the lender but not always. Fourth, exit or deeds-release fees from your old lender, usually small but worth checking.
Prepare your credit file three months ahead: check all three agencies, correct errors, make sure you are on the electoral roll at your current address, and avoid new credit applications in the final weeks. Keep payslips, bank statements and proof of address ready so an application does not stall. If you are considering paying down the balance before switching to reach a better loan-to-value band, weigh that against keeping an emergency fund — our guide to mortgage overpayments explains how extra payments work once a deal is running. Finally, if you expect rates to fall, you have two bridges: reserve a deal now and switch before completion if rates drop, or take a tracker — it follows the Bank of England base rate, usually has no early repayment charge, and lets you fix later. Only choose a tracker if you could afford the payment if rates rose instead.
Frequently Asked Questions
What happens if I do nothing when my fix ends?
You move automatically onto your lender’s standard variable rate. Your payment will usually rise, the rate can change at any time, but you will normally be free of early repayment charges, so you can switch whenever you are ready.
How early can I arrange a new mortgage deal?
Most lenders let you reserve a deal three to six months before your current fix ends, with completion set for just after the end date. Reserving early protects you if rates rise, and you can often change if they fall.
Is a product transfer easier than remortgaging?
Yes, usually. It stays with your current lender, often needs no valuation or legal work, and involves lighter checks. It is not always the cheapest option, so compare its total cost against the wider market before accepting.
Will switching lenders affect my credit score?
A full remortgage application involves a hard credit search, which can cause a small, temporary dip. A product transfer with your existing lender often involves no hard search at all. Space out other credit applications around the same period.



